Plan the scope
Understand the proposed pool, features and related work before choosing an amount to borrow.
Turning Your Dream Pool into Reality starts with a clear project scope and a careful look at financing options. Explore Lyon Financial’s calculator and learn what to review before you apply.
Lyon Financial is Cove & Stone’s primary pool-financing partner. Financing and approval are determined by the lender.
Enter a loan amount, interest rate and amortization period in Lyon Financial’s calculator to view an estimate. Use a rate supplied by the lender; the result is not an offer or loan approval.
The calculator is hosted by Lyon Financial. Its estimate, application, privacy practices and terms are controlled by Lyon Financial; actual rates, payments, fees, eligibility and approval depend on the lender and the terms offered to you.
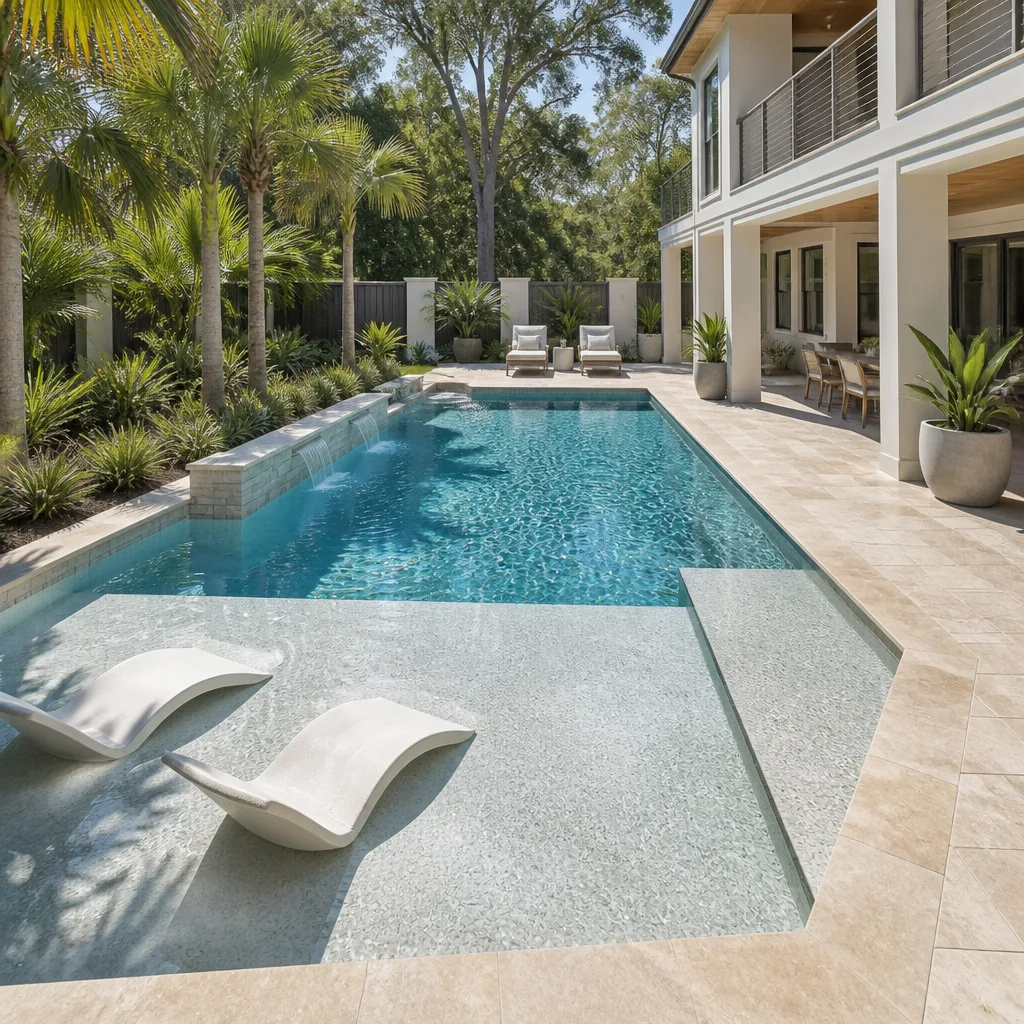
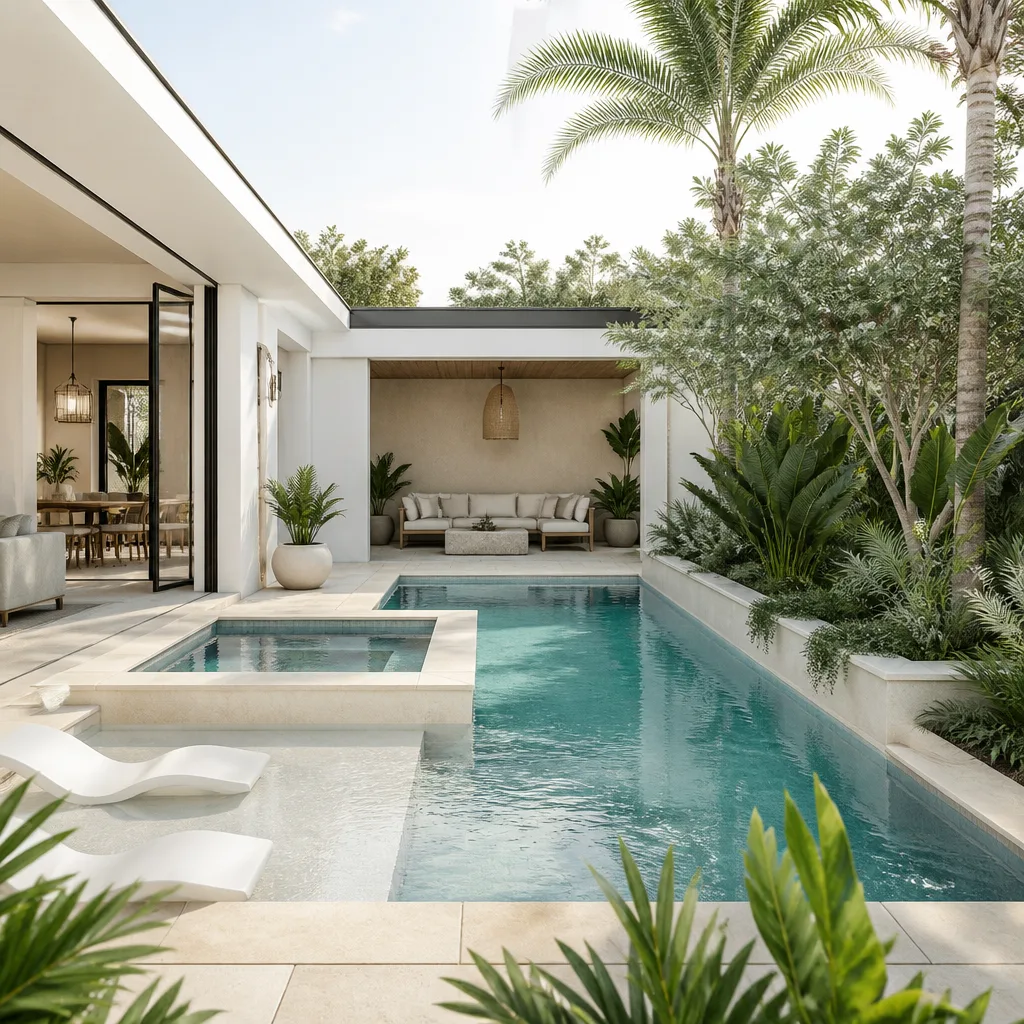
A project estimate is easier to discuss when you can picture the space. These illustrative concepts show different design directions; they are not photographs of completed Cove & Stone projects.
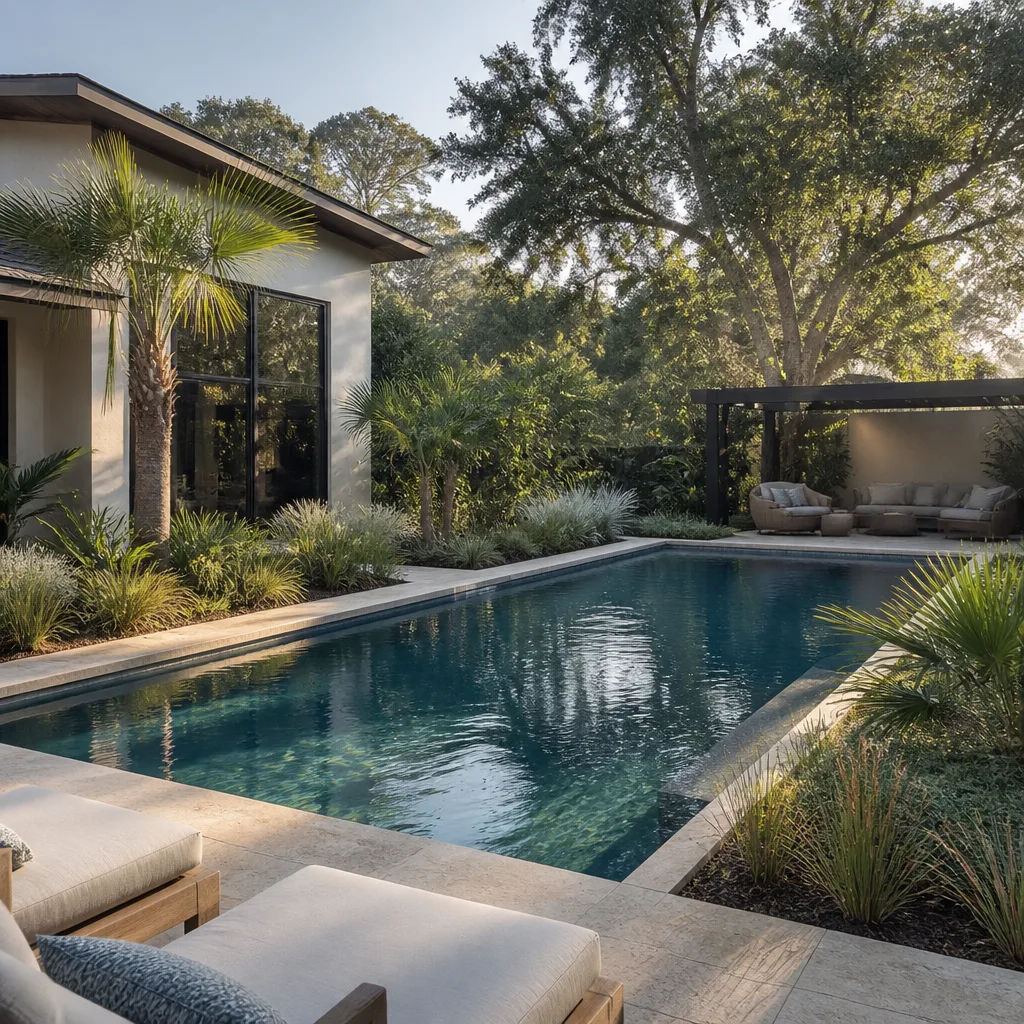
Eligibility is decided by the lender, based on its current program rules and review of an applicant’s financial profile. A lender may consider credit history, income, existing obligations, requested amount and project information. Not every applicant will qualify, and Cove & Stone cannot predict or guarantee a decision.
Financing may let a homeowner spread project costs over time rather than pay the full amount up front. Whether that makes sense depends on the complete cost of borrowing, the household budget and the written loan terms—not just an estimated monthly payment.
For some homeowners, financing can make project timing and cash flow easier to plan. It is not automatically the lowest-cost choice: interest and fees can increase the total paid. Compare a financing plan with paying from savings and other options before deciding.
Understand the proposed pool, features and related work before choosing an amount to borrow.
Look at the rate, term, fees and expected total repayment alongside the monthly estimate.
Allow for ongoing pool care and household expenses as well as project payments.
Pool financing options differ in how they are secured, how funds are accessed and how rates and payments work. The right comparison depends on current offers and your circumstances.
A lender focused on pool or home-improvement projects may offer a process designed around those project costs. Programs, loan structures and eligibility vary by lender and can change.
Cove & Stone lists Lyon Financial as its primary pool-financing partner. Lyon’s calculator lets you enter a loan amount, interest rate and amortization period to estimate a monthly payment. The calculator is hosted by Lyon Financial; its terms and application process are controlled by the lender.
Visit Lyon Financial’s pool loan calculatorSuppose a homeowner has a written project estimate and is comparing financing. They can enter the amount they may borrow, a rate quoted by the lender and a proposed term in Lyon’s calculator, then compare the estimate with their budget. This is an example workflow, not a Cove & Stone customer story or a loan offer.
A HELOC is a revolving credit line that is commonly secured by home equity. A lender sets the credit limit and rules for drawing and repayment. Because the home may secure the line, missed payments can put the home at risk; review the lender’s documents and consider independent financial advice.
After an application and lender review, an approved borrower may draw from the line under the agreement’s rules. The draw period, repayment period, rate, fees and available credit depend on that lender and product.
A HELOC may provide access to funds in stages and may offer a different rate or repayment structure from a pool loan. Weigh that flexibility against variable-rate exposure, fees, repayment terms and the risk of borrowing against your home.
These are general differences, not a recommendation. Ask each provider for current terms and compare offers using the same project amount and repayment assumptions.
| What to compare | Specialized pool financing | Home equity line of credit |
|---|---|---|
| How it is based | Lender program and borrower application | Home equity and lender underwriting |
| Rate structure | Check whether the offer is fixed or variable | Often variable; confirm the actual agreement |
| Collateral | Depends on the particular loan | Commonly secured by the home |
| Key questions | APR, term, fees, payment and early-payoff rules | Rate changes, draw/repayment periods, fees and home risk |
Assess Your Needs. Decide which parts of the backyard project matter most, such as the pool, spa, deck, shade, lighting or outdoor-living features.
Estimate Costs. Start with a project scope and written estimate where available. Include related work, engineering, permitting, equipment and selections that are part of the plan.
Compare Financing Methods. Review a pool loan and any HELOC or other option you are considering. Compare APR, fixed or variable rate, term, fees, collateral, payment schedule and total repayment—not only the first monthly estimate.
What You’ll Need. Each lender gives its own checklist. It may request identity, income, existing obligations and project information. Send financial documents directly through the lender’s secure process.
Submit the completed application to the lender, not to Cove & Stone. Review consent language and disclosures before sending personal or financial information.
The lender reviews the application and determines eligibility, available terms and any conditions. Approval and timing are not guaranteed; respond to lender requests and review the final written offer carefully.
Funding method and timing depend on the agreement. Confirm how funds are disbursed, when payments begin and whether the lender requires project documentation before funds are released.
Coordinate financing milestones with the confirmed project scope, contract, approvals and construction schedule. Start only when the project and funding requirements are clear.
Additional Considerations for Pool Financing include costs beyond the monthly payment, possible credit inquiries and whether the requested amount covers the features in your confirmed project scope.
A fixed rate stays steady for the period stated in the agreement, which can make scheduled payments more predictable. Confirm the rate period and all conditions.
A variable rate can change under the contract’s rules, which may change the payment or total interest. Ask what index, margin, caps and adjustment schedule apply.
A longer term may reduce a scheduled payment but can increase total interest if other terms are similar. Compare both payment and total repayment.
Consider the estimated payment alongside household obligations, utilities, insurance and future pool maintenance. Leave room for changes in costs and income.
Ask whether extra payments, a different due date or payment changes are allowed and whether they create fees. The signed agreement controls.
Check the contract for prepayment penalties, payoff fees and how additional payments are applied before assuming you can repay early at no cost.
Compare the effect of extra payments with keeping emergency savings and meeting other financial goals. Ask the lender for payoff figures and rules.
Ask about any origination, application, closing, appraisal, annual or early-termination charges that may apply. Request a written itemization.
Ask whether checking eligibility involves a soft or hard credit inquiry, when an inquiry occurs and how an application may affect your credit profile.
If you include a spa, upgraded finishes, lighting, decking or outdoor-living features, confirm that the lender accepts those costs and how they affect the amount requested.
Our role is to help clarify the pool and outdoor-living scope so you have project details to discuss with a lender. Financing decisions, product recommendations and approvals belong to you and the lender.
Lyon Financial is our primary pool-financing partner. Current offers and additional program availability must be confirmed with the lender.
Discuss the features and selections you want included so the proposed project scope is clearer before you compare options.
We can help coordinate project questions and next steps; we cannot advise on loan suitability or see a lender’s credit decision.
Enter a loan amount, interest rate and amortization period to see an estimated monthly payment. It is an estimate, not a loan offer or approval. Ask Lyon Financial for current rates, terms and disclosures.
Eligibility depends on the lender’s current program rules and review of the applicant’s financial profile. Not all applicants qualify, and Cove & Stone cannot predict or guarantee a lender decision.
No. Cove & Stone is not a lender and does not make credit decisions. Contact Lyon Financial or another participating lender directly for current rates, terms, payments, eligibility and complete program details.
A HELOC is commonly secured by home equity and may have a variable rate, draw period and repayment period. Terms and risks vary, so compare the written agreement with any pool-loan offer and seek qualified financial advice if needed.
No. The calculator displays an estimate based on the inputs entered. Actual rates, payments, fees, eligibility and approval are determined by the lender and may differ.
Contact us today to begin a conversation about your property, project scope and next steps. For loan terms or an application decision, speak directly with Lyon Financial.